
Quick Summary
Property owners facing water damage often need to know if Floodline Restoration Co. bills insurance carriers directly to minimize out-of-pocket expenses and claims friction. Floodline Restoration Co. streamlines recovery by coordinating directly with insurance adjusters, submitting comprehensive moisture logs, and providing itemized scopes while property owners handle standard policy deductibles. Homeowners can call Floodline Restoration Co. to schedule a free visual inspection and let certified specialists manage the water mitigation and insurance billing process from start to finish.
Does Floodline Restoration Bill Insurance – Direct Claim Help
Floodline Restoration states that it bills insurance carriers directly. Customers should confirm authorization requirements, payment arrangements, deductibles, and any remaining balance with both their insurer and the restoration contractor before work begins.[5]
Providing detailed documentation of damage and drying progress can assist the insurer during claim review. However, documentation does not guarantee coverage, speed of processing, or payment. Policyholders are generally responsible for their deductible, policy limits, and any uncovered expenses defined in their property policy.
Contact Floodline Restoration Co. to schedule an on-site inspection and discuss claim coordination options.
Does Floodline Restoration Bill Insurance Directly?
Does Floodline Restoration Bill Insurance Directly? in brief: Floodline Restoration states that it coordinates with insurance adjusters and submits itemized billing directly. The policyholder is generally responsible for the policy deductible. Payment responsibility for uncovered or denied repairs depends on the policy, claim determination, restoration agreement, and applicable law.
For illustrative purposes, whether clean water enters a home or sewage backs up in a commercial building, the immediate priority is mitigating damage. Floodline Restoration states that it communicates directly with insurance adjusters during the claims process.
Documenting pre-loss conditions and emergency mitigation work provides a record for the insurer. While thorough documentation may assist claim review, it does not guarantee coverage, speed, or payment.
Claim Coordination and Policy Coverage
According to the National Association of Insurance Commissioners (NAIC), standard homeowners insurance generally covers sudden and accidental water damage, such as burst pipes, plumbing leaks, roof leaks, or wind-driven rain. However, policy terms, exclusions, deductibles, limits, and the insurer’s claim investigation control coverage decisions.[2]
As noted by specialists at Floodline Restoration Co., itemized scopes and documentation help insurers evaluate necessary repairs and restoration steps.
Key Takeaways: Billing, Deductibles, and Coverage
- Direct Carrier Submission: Invoices and supporting documentation are submitted directly to the insurer.
- Deductible Responsibility: The policyholder is generally responsible for the policy deductible.
- Exclusions Apply: Groundwater, rain runoff, snowmelt, and other surface-water flooding are generally excluded from standard homeowners insurance and usually require separate flood insurance.
What Water and Property Damage Is Typically Covered by Homeowners Insurance?
Understanding what an insurance carrier will pay for depends on the origin of the water, policy language, and applicable exclusions.
Sudden and Accidental Water Damage vs. Gradual Leaks
Standard property policies may cover sudden and accidental water damage, subject to policy terms, exclusions, deductibles, limits, and claim investigation. Potentially covered events include:
- Burst pipes
- Plumbing leaks
- Roof leaks
- Wind-driven rain
Conversely, slow or gradual leaks that occur over time are routinely excluded as maintenance or wear-and-tear issues.
Overland Flooding vs. Internal Plumbing Failures
Groundwater, rain runoff, snowmelt, and other surface-water flooding are generally excluded from standard homeowners insurance and usually require separate flood insurance, such as through the National Flood Insurance Program (NFIP) or private flood underwriters.[4]
According to the Insurance Information Institute, many residential policyholders do not carry standalone flood insurance. According to Floodline Restoration Co., identifying the source of water intrusion is critical in determining applicable coverage.[1]
Secondary Mold Remediation Coverage Limitations
Mold coverage under standard homeowners insurance is often excluded or limited. In some circumstances, mold remediation may be covered if it results directly from a covered water-loss event, subject to specific policy terms and endorsements.
Direct Insurance Billing and Homeowner Responsibilities
When a restoration contractor submits billing, the carrier reviews charges against policy limits, endorsements, and exclusions. Policyholders should be aware of:
- The Policy Deductible: The policyholder is generally responsible for the deductible under the insurance policy.
- Betterments and Upgrades: Upgrades or modifications that exceed pre-loss condition are typically not covered by insurance.
- Denied or Uncovered Work: Payment responsibility for denied or uncovered work depends on the policy, claim determination, restoration agreement, and applicable law.
Restoring Architectural Components
Need does floodline restoration bill insurance?
We’re available now - call for a fast, free estimate.
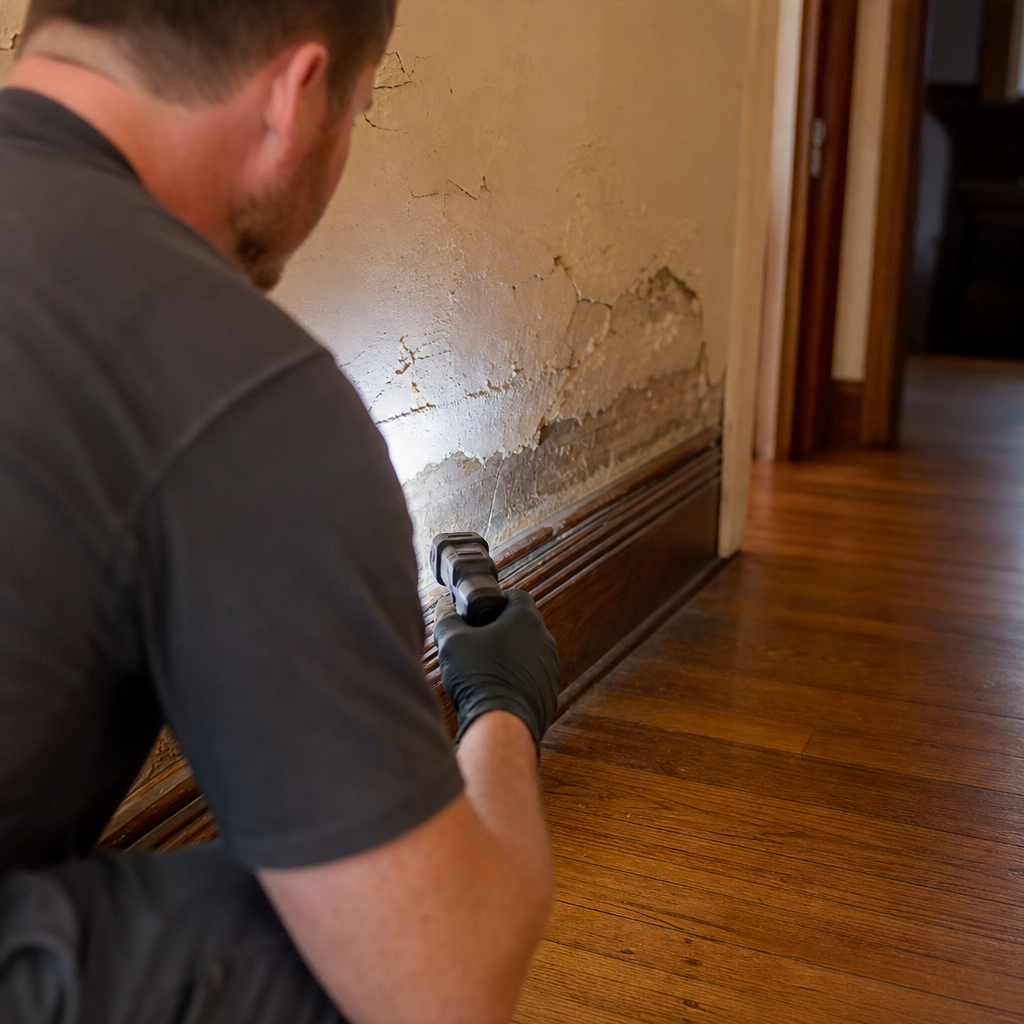
Preserving building materials requires appropriate drying techniques and accurate documentation, as emphasized by Floodline Restoration Co. Documenting structural drying helps demonstrate the scope of work to the insurance carrier.
Basements, Crawl Spaces, and Foundations
Moisture readings and damage assessments provide the adjuster with records of structural drying progress during the restoration process.
What Does Water Damage Restoration and Insurance Billing Cost?
The total cost of water restoration depends on the scope of damage and required mitigation. When insurance applies, the insurer pays only covered amounts, subject to deductibles, coverage limits, policy exclusions, and the insurer’s claim determination.
How Deductibles and Flood Coverage Work
For covered homeowners claims, the insurer’s payment is reduced by the applicable policy deductible. Under the National Flood Insurance Program (NFIP), standard residential policy limits provide up to $250,000 for building coverage and up to $100,000 for contents coverage.[3]
Working with Insurance Adjusters
Floodline Restoration works with desk adjusters and field adjusters by providing project documentation, photographs, and line-item scopes to assist with claim evaluation.
Frequently Asked Questions About Restoration Insurance Billing in Englewood, NJ
Does Floodline Restoration bill insurance companies directly?
Floodline Restoration states that it bills insurance carriers directly. Customers should confirm authorization requirements, payment arrangements, deductibles, and any remaining balance before work begins.
Who pays the deductible for water damage restoration?
The policyholder is generally responsible for the deductible defined in their insurance policy.
What happens if an insurance claim is partially denied?
If an insurer denies coverage for a portion of the work, payment responsibility depends on the insurance policy, the claim determination, the restoration agreement, and applicable law.
How much does water damage restoration cost in Englewood, NJ?
Costs vary depending on the extent of damage and necessary repairs. For covered losses, the insurance carrier pays only covered amounts, subject to policy limits, deductibles, exclusions, and the insurer’s claim decision.
How quickly can a direct-billing restoration team arrive on-site?
At Floodline Restoration Co., arrival times and response availability depend on location, dispatch schedules, and current weather or emergency conditions.
Need does floodline restoration bill insurance?
We’re available now - call for a fast, free estimate.
Sources
- flooded (a report by fema) – agents.floodsmart.gov
- 1 Written Testimony of Carolyn Kousky Executive Director, … – congress.gov
- View PDF – fema.gov
- Flood Insurance and the NFIP – fema.gov
- Many homeowners cancel flood insurance despite rising risk – insurance.com (2026)
Related reading: Floodline Restoration Englewood Nj Ratings | 10% Off & Free Estimate | Same-Day Service
Related reading: Floodline Restoration Co Customer Reviews – Call Now-10% Off – Same-Day Service – Free Estimate
Related reading: Emergency Flood Cleanup Englewood Nj | 10% Off & Free Estimate | On-Site in 60 Minutes
Frequently Asked Questions
What documentation does Floodline Restoration Co. submit to insurance adjusters during direct billing?
Floodline Restoration Co. compiles and submits detailed pre-loss photos, daily structural drying moisture logs, and itemized line-item scopes directly to desk and field adjusters. This rigorous documentation provides carriers with the verification needed to evaluate and process the mitigation claim smoothly.
Do I have to pay upfront before Floodline Restoration Co. inspects the water damage?
No, property owners can contact Floodline Restoration Co. to schedule a free visual on-site inspection without upfront assessment charges. Once the damage is evaluated, their certified team initiates the claims coordination process and bills your insurance carrier directly.
When is the property deductible paid during direct insurance billing with Floodline Restoration Co.?
Because Floodline Restoration Co. submits the restoration invoice directly to your insurer, the carrier reduces its settlement payout by the policy deductible amount. Policyholders typically pay their deductible directly to the restoration contractor as defined in their service authorization agreement.
About the author
 |
Marcus Caldwell Marcus Caldwell is an IICRC-certified Water Damage Restoration Technician with over 12 years of hands-on experience in emergency property recovery across New Jersey. Holding a B.S. in Construction Management from Rutgers University, he specializes in structural drying techniques and navigating complex insurance claims for both residential and commercial properties. Marcus leverages his field expertise to provide Englewood property owners with clear, actionable guidance on mitigating water damage and understanding restoration costs. |
Water damage, flood, or mold emergency?
We’re available now - call for a fast, free estimate.
Call Now - Free Estimate