
Quick Summary
Navigating property water damage claims can be financially and administratively overwhelming without proper carrier-standard scope documentation. Floodline Restoration Co. streamlines recovery through direct floodline restoration insurance billing, submitting verified moisture logs and itemized estimates straight to adjusters. Readers will understand how direct billing minimizes upfront expenses and can contact Floodline Restoration Co. to initiate emergency mitigation and seamless claim management.
Floodline Restoration Insurance Billing: Direct Carrier Claims and Scope Documentation
Managing water damage in a residential property or commercial facility requires fast physical containment and precise administrative coordination. Floodline Restoration Co. provides water mitigation, structural drying, and direct insurance billing across Englewood, New Jersey. Through direct carrier billing, our team submits itemized mitigation estimates and documentation straight to your property insurance carrier, keeping your claim moving without leaving you stuck in the middle.[5]
When unexpected water intrusions strike, navigating carrier requirements can feel overwhelming. Whether a property insurance policy covers water damage depends on the policy, cause of loss, exclusions, limits, and insurer determination. Adjusters require objective documentation before approving mitigation invoices. By aligning physical drying procedures with standard documentation practices, Floodline helps ensure mitigation work is supported from day one.[4]
How Direct Insurance Billing Works for Property Water Damage
Direct insurance billing through Floodline Restoration Co. removes the burden of paying full mitigation costs upfront and fighting for reimbursement later. Instead of handing you a large out-of-pocket bill after drying out your property, Floodline works directly with your insurance carrier’s claims department and assigned adjuster.
Under this structure, our team opens a direct line of communication with the insurer and submits itemized line-item scopes to document the work performed. The customer is responsible for the policy deductible, while any uncovered work, exclusions, limits, or charges beyond approved coverage may also remain the customer’s responsibility.
What You Need Before Initiating a Restoration Claim
- Prompt Notification: Contact your insurer promptly to report the loss, obtain a claim number, and confirm whether an adjuster inspection is required before repairs begin.
- Loss and Damage Documentation: Capture clear photographs or video showing standing water, affected areas, and building materials before cleanup begins.
- Expense and Communication Records: Retain detailed records of all claim-related expenses, receipts, and correspondence with your insurer and contractors.
Step 1: Emergency Loss Containment and Claim Initiation
The first priority during any water emergency is stopping the water source, extracting standing water, and securing the structure. Rapid response helps stop water from migrating deep into subfloors, wall cavities, and lower levels.
During initial containment, technicians establish an official claim record. This includes recording initial moisture readings, documenting the source of water intrusion, and evaluating the water category to determine appropriate mitigation protocols.
Step 2: Moisture Mapping and Documentation
Insurance adjusters base coverage approvals on verifiable field data. Immediately after containment, Floodline Restoration Co. technicians document moisture conditions across affected areas of the property.
Technicians record data points across affected areas:
- Moisture Content Readings: Establishing baseline saturation in structural materials compared to dry standards.
- Atmospheric Tracking: Monitoring temperature and relative humidity in affected areas.
- Photographic Logs: Detailed room-by-room photographic evidence showing damage, water migration paths, and equipment placement.
Step 3: Direct Claim Filing and Standard Scope Creation
Once the initial inspection is complete, Floodline builds an itemized scope using standard restoration billing codes. This provides the carrier with a line-by-line breakdown of equipment, labor, and materials.
| Billing Feature | Floodline Direct Carrier Billing | Traditional Contractor Reimbursement | Assignment of Benefits (AOB) |
|---|---|---|---|
| Payment Workflow | Billed directly to insurance; owner covers deductible and non-covered items | Property owner pays upfront, then seeks reimbursement | Third party manages claim rights according to agreement |
| Estimating Format | Itemized line-item scope | Lump-sum or generic estimate | Variable third-party format |
| Moisture Tracking | Moisture documentation provided to adjuster | Varies by contractor | Varies by third-party company |
Step 4: Controlled Structural Drying and Monitoring
Need floodline restoration insurance billing?
We’re available now - call for a fast, free estimate.
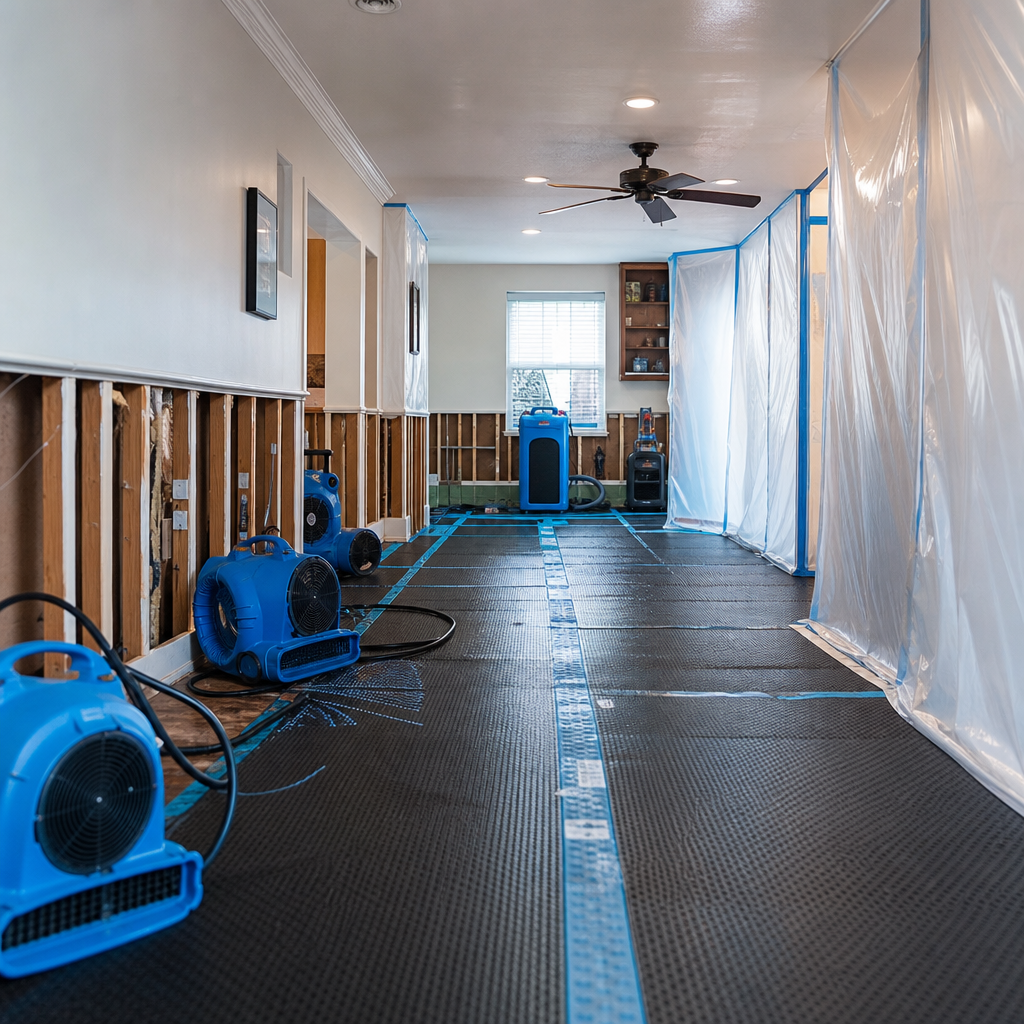
Drying structural elements in residential and commercial spaces requires proper airflow and moisture extraction. In structures with trapped moisture, improper drying can lead to secondary damage.
Floodline uses commercial dehumidifiers and air movers to extract trapped moisture from affected building materials. Technicians monitor moisture changes and log progress toward dry-standard benchmarks to justify the equipment run times submitted on your insurance invoice.
Step 5: Submitting Itemized Scopes to the Insurance Adjuster
When the drying phase concludes, our administrative team compiles the final mitigation package. This file includes the initial work authorization, moisture logs, drying progress photos, and the finalized line-item estimate.
By providing complete technical documentation, Floodline Restoration Co. assists adjusters in reviewing the claim file. If an adjuster requests clarification regarding equipment run times or drying procedures, our billing staff communicates directly with them to provide the underlying logs.
Step 6: Claim Settlement and File Closeout
Once the carrier approves the mitigation invoice, payment is issued directly according to your policy terms. Our administrative team assists with file closeout to ensure all mitigation documentation is properly finalized with your insurer.
National Flood Insurance and Private Water Damage Context
Understanding the difference between private homeowners insurance and federal flood insurance is vital when managing water damage claims. Whether private insurance covers water damage depends on the policy, cause of loss, exclusions, limits, and insurer determination, while overland flooding typically requires separate flood insurance.[2]
On a national scale, the NFIP provides approximately $1.3 trillion in flood coverage to nearly 4.7 million policyholders nationwide. As of March 31, 2025, the NFIP covered approximately 4.7 million active policies in more than 22,700 communities across all 50 states and six U.S. territories. The NFIP had processed more than 2.7 million claims between 1968 and 2025, and FEMA stated that the NFIP pays eligible claims according to the terms of policyholders’ flood insurance policies. These federal statistics reflect NFIP program operations and do not establish private-insurance billing requirements.[1]
Understanding Out-of-Pocket Costs and Deductibles
When using direct insurance billing with Floodline Restoration, financial expectations remain clear throughout the process. The customer is responsible for the policy deductible, while any uncovered work, exclusions, limits, or charges beyond approved coverage may also remain the customer’s responsibility.
Additional out-of-pocket expenses may apply if your policy contains specific sub-limits, if certain damaged items fall outside policy guidelines, or if you choose optional upgrades beyond the pre-loss restoration scope. Floodline Restoration Co. reviews your billing file so you understand all financial aspects before work proceeds.
Frequently Asked Questions About Restoration Insurance Billing
Does Floodline Restoration bill insurance companies directly?
Yes. Floodline Restoration bills most major insurance carriers directly for covered water mitigation services. We submit itemized line-item invoices, moisture records, and photo documentation directly to your carrier’s claims department.[3]
Which insurance providers work with Floodline Restoration?
The available source says Floodline bills most major insurance carriers directly, but specific providers could not be confirmed from the provided research.
How do I file an insurance claim for water damage?
To file a claim, promptly notify your insurance carrier to report the loss, obtain a claim number, and confirm whether an adjuster inspection is required before repairs. Thoroughly document damage with photos or video, retain expense and communication records, and contact Floodline Restoration to begin mitigation and documentation.
What out-of-pocket costs or deductibles am I responsible for?
The customer is responsible for the policy deductible, while any uncovered work, exclusions, limits, or charges beyond approved coverage may also remain the customer’s responsibility.
Does homeowners insurance cover emergency water extraction and drying?
Coverage depends on the policy, cause of loss, exclusions, limits, and insurer determination.
How long does the restoration insurance billing process take?
Flood-insurance claim finalization and payment generally take four to eight weeks, noting that actual timing varies and that this timeframe may not apply to private water-damage claims.
Need floodline restoration insurance billing?
We’re available now - call for a fast, free estimate.
Sources
- nfip_by-the-numbers-summary_20251031.xlsx – agents.floodsmart.gov (2025)
- FEMA Exercises Borrowing Authority for National Flood … – fema.gov (2025)
- Hurricane Milton – floir.gov (2025)
- How to start a flood insurance claim – floodsmart.gov (2024)
- national flood insurance program – media toolkit – agents.floodsmart.gov (2024)
Related reading: Does Floodline Restoration Bill Insurance – 10% Off & Free Estimate – Same-Day Service
Related reading: Floodline Restoration Co Customer Reviews – Call Now-10% Off – Same-Day Service – Free Estimate
Related reading: Emergency Flood Cleanup Englewood Nj | 10% Off & Free Estimate | On-Site in 60 Minutes
Frequently Asked Questions
What happens if an insurance adjuster questions or disputes the mitigation invoice?
Floodline Restoration Co. resolves adjuster inquiries directly by submitting verifiable moisture logs, atmospheric readings, and photographic documentation collected throughout the drying process. Our administrative team works directly with your carrier to justify line-item scopes and equipment run times, eliminating disputes without putting you in the middle.
Does direct insurance billing require signing an Assignment of Benefits (AOB)?
No, Floodline Restoration Co. does not require an Assignment of Benefits agreement to coordinate with your insurance carrier. Our direct billing workflow submits itemized, carrier-standard invoices directly to your insurer while ensuring you retain full ownership and control of your policy rights.
How quickly can Floodline Restoration Co. dispatch a team and begin claim documentation?
Floodline Restoration Co. operates a 24/7 live dispatch center to deploy emergency mitigation technicians immediately upon contact. Our crew establishes your official claim file on day one by capturing baseline moisture readings, water migration photos, and damage reports to accelerate insurer approval.
About the author
 |
Marcus Caldwell Marcus Caldwell is an IICRC-certified Water Damage Restoration Technician with over 12 years of hands-on experience in emergency property recovery across New Jersey. Holding a B.S. in Construction Management from Rutgers University, he specializes in structural drying techniques and navigating complex insurance claims for both residential and commercial properties. Marcus leverages his field expertise to provide Englewood property owners with clear, actionable guidance on mitigating water damage and understanding restoration costs. |
Water damage, flood, or mold emergency?
We’re available now - call for a fast, free estimate.
Call Now - Free Estimate