
Quick Summary
Navigating floodline restoration co insurance claims after property damage requires comprehensive documentation and adjuster coordination to secure proper coverage. Floodline Restoration Co. simplifies the process by delivering carrier-standard scopes, moisture logs, and visual evidence directly to adjusters to expedite claim evaluation. Readers will learn how coverage applies to different water damage scenarios and how to contact Floodline Restoration Co. for 24/7 emergency dispatch and complete claim documentation assistance.
Floodline Restoration Co. Insurance Claim Assistance and Documentation
Filing a property damage claim after a pipe burst, appliance leak, or storm can involve coordinating mitigation and providing documentation to insurance carriers. In Englewood and across Bergen County, Floodline Restoration Co. documents property losses, tracks moisture readings, and prepares scopes of work that may help the insurer evaluate the claim.[5]
When emergency water or fire damage occurs, Floodline Restoration Co. provides on-site documentation, including photographs, moisture readings, and documented work, to assist in presenting the details of the loss to your carrier. See also What to Do When a Pipe Bursts | Call Now-10% Off | Same-Day Service | Free Estimate.
How Floodline Restoration Co. Insurance Claim Documentation Works
How Floodline Restoration Co. Insurance Claim Documentation Works in brief: Floodline Restoration Co. pairs emergency mitigation with documentation practices such as photographs, moisture readings, and documented work. Floodline states that it prepares scopes in an estimating format used by insurance carriers. Additional services, such as psychrometric logs or thermal imaging, are possible services if independently documented. This documentation may help the insurer evaluate the claim.
When insurance adjusters assess a property loss, documentation of the loss conditions is typically reviewed. The restoration team documents conditions from the start of mitigation work through structural drying.
What Is Included in Claim Documentation
For water damage claims, adjusters review specific loss details. Mitigation specialists provide claim documentation that includes:
- Photographs: Photos capturing initial structural conditions, source areas, water lines, and documented work. Thermal imaging may be provided as a possible service if independently documented.
- Moisture Readings: Moisture readings from structural materials recorded to track drying progress. Psychrometric logs and atmospheric data may be included as possible services if independently documented.
- Written Carrier-Format Scope: Floodline states that it prepares scopes in an estimating format used by insurance carriers. Additional details, such as equipment runtimes or floor plans, may be included as possible services if independently documented.
Key Considerations for Adjuster Coordination
Coverage varies by policy and cause of loss, and navigating the claims process involves coordinating documentation with the field adjuster assigned to the file.
According to the Insurance Information Institute, flood damage caused by rising groundwater, outdoor runoff, and surface water is generally separate from standard homeowners insurance and may require NFIP or private flood insurance. In contrast, sudden and accidental internal water discharges, such as frozen pipes, failed supply lines, or water heater failures, are generally reviewed under standard property coverage depending on policy terms.
Documenting Water Damage and Moisture Migration in Pre-War Structures
In older and pre-war homes, water can travel through plaster-and-lath walls or balloon-framed wall cavities differently than in modern drywall construction. Anecdotally, deep-cavity moisture migration within these assemblies can sometimes be questioned as pre-existing moisture or environmental humidity.
When a pipe bursts in a balloon-framed structure, water can travel down open vertical wall cavities. Plaster and wood lath retain moisture longer than drywall, which can result in elevated moisture readings over time. Documenting moisture readings and physical damage helps record the path of the water discharge to assist the carrier in evaluating the claim.
Regional Flood Claim Context and Policy Definitions
Widespread weather events in recent years have placed massive demands on regional and national recovery funds. For example, FEMA exercised $2 billion in borrowing authority in 2025 to pay eligible National Flood Insurance Program (NFIP) policyholder claims following extreme rainfall and storm events across the country, including Hurricanes Helene and Milton. Nationwide, the NFIP operates across approximately 22,500 communities to deliver specialized flood protection.[1]
While federal programs track these large-scale regional totals, available national statistics do not provide a current, verified claim count or payout total specifically for Englewood, New Jersey. Coverage varies by policy and cause of loss, and flood damage is generally separate from standard homeowners insurance and may require NFIP or private flood insurance.[2]
What Does Restoration Insurance Claim Assistance Cost?
Need floodline restoration co insurance claims?
We’re available now - call for a fast, free estimate.
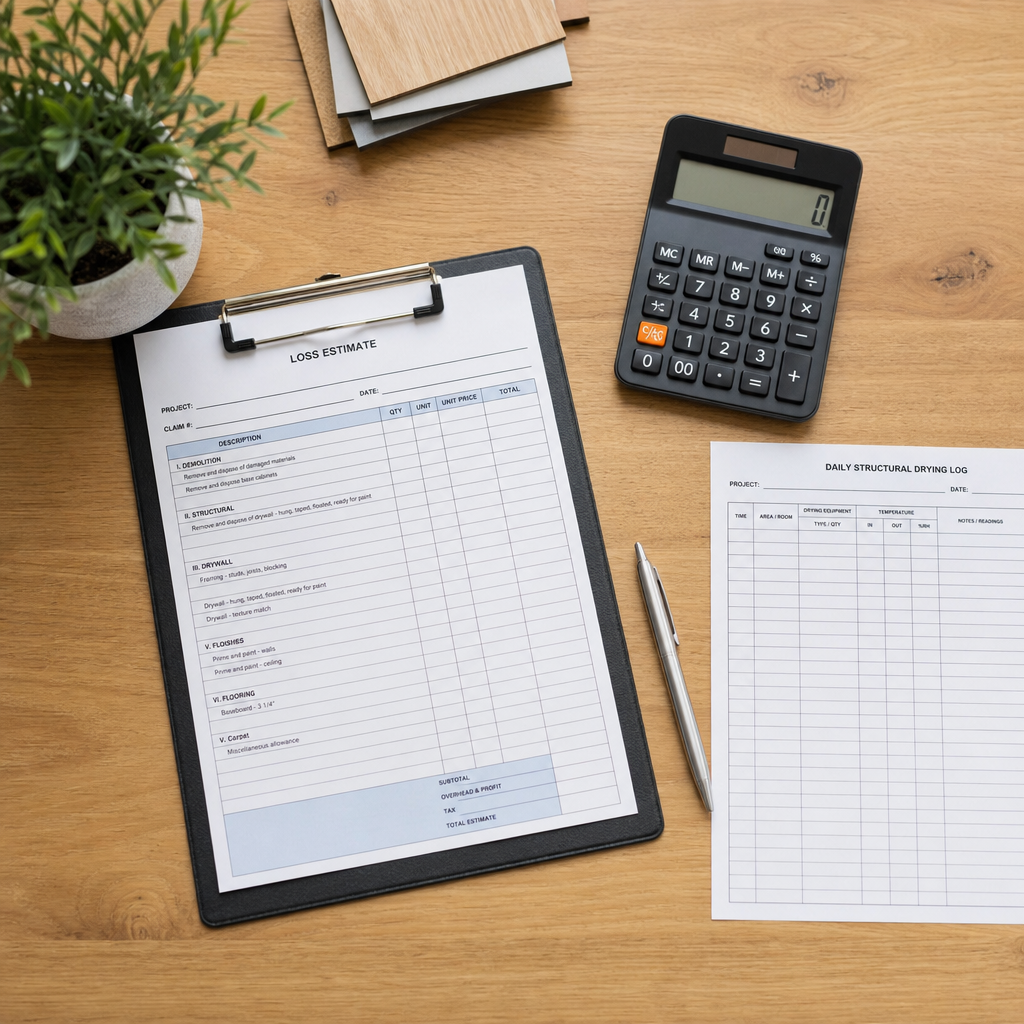
The policyholder’s financial responsibility and insurer payment depend on policy terms, coverage, exclusions, limits, deductible, cause of loss, and claim approval. Costs for mitigation and drying services are submitted to the insurer for review under the claim file.
Understanding Policy Deductibles and Direct Billing
Your insurance deductible is the portion of the claim you are contractually responsible for paying according to your insurance policy terms. The mitigation team provides billing documentation, submitting itemized scopes, moisture readings, and documented work to help the insurer evaluate the claim, though this does not guarantee acceptance or timing.
Providing line-item documentation before work advances beyond emergency stabilization helps outline the scope of services under review.
Insurance Carrier and Adjuster Communication
Managing an insurance claim involves technical documentation. Restoration professionals can provide documentation such as moisture readings and scopes of work to assist adjusters during claim evaluation.
Preserving Architectural Materials
When practical, drying structural materials in place may be considered alongside standard mitigation methods. Documenting drying progress and structural conditions provides the carrier with data regarding the mitigation process, though coverage and approved methods remain subject to insurer review.
Frequently Asked Questions About Property Damage Claims in Englewood
Frequently Asked Questions About Property Damage Claims in Englewood in brief: Coverage for water, fire, or mold damage depends on policy terms, the underlying cause of loss, exclusions, and limits. Mold coverage may be excluded or limited, depending on the policy. Documentation may help the insurer evaluate the claim, though approval and timing are not guaranteed.
Coverage, Timelines, and Local Response Details
Does Floodline Restoration Co. work directly with homeowner insurance companies?
Floodline Restoration Co. provides documentation, such as photographs, moisture readings, documented work, and carrier-format scopes, to help adjusters and insurance representatives evaluate the claim.
How does Floodline Restoration Co. assist with filing water damage insurance claims?
The team assists by documenting affected structural components, recording moisture levels, and compiling an itemized scope. Floodline states that it prepares scopes in an estimating format used by insurance carriers. This documentation may help the insurer evaluate the claim, without guaranteeing acceptance or timing.[3]
Will standard homeowner insurance cover water, fire, and mold restoration services?
Coverage varies by policy and cause of loss. Sudden and accidental water discharges and fire losses may be covered depending on policy terms and limits. Mold coverage may be excluded or limited, depending on the policy. Flood damage is generally separate from standard homeowners insurance and may require NFIP or private flood insurance.
What claim documentation does Floodline Restoration Co. submit to insurance adjusters?
The team submits photographs, moisture readings, documented work, and a written carrier-format scope. Thermal imaging, psychrometric logs, floor plans, and equipment runtimes are possible services if independently documented.
Do I have to pay my insurance deductible directly to Floodline Restoration Co.?
The policyholder is responsible for the deductible under the policy, but payment arrangements with the contractor should be confirmed in the contract and with the insurer.[4]
How long does the insurance claim approval process take for water mitigation?
Claim review times vary by insurer, claim complexity, documentation, and applicable policy requirements.
Need floodline restoration co insurance claims?
We’re available now - call for a fast, free estimate.
Sources
- FEMA Exercises Borrowing Authority for National Flood … – fema.gov (2025)
- https://crsreports.congress.gov – congress.gov (2024)
- Closing the Flood Insurance Gap – congress.gov (2024)
- flooded (a report by fema) – agents.floodsmart.gov (2009)
- FEMA borrows $2 billion to pay flood insurance claims … – cbsnews.com (2024)
Related reading: Floodline Restoration Co Response Time | Call Now-10% Off | Same-Day Service | Free Estimate
Related reading: Sewage Backup Cleanup | Call Now-10% Off | Same-Day Service | Free Estimate
Related reading: Who to Call When a Pipe Bursts | Call Now-10% Off | Same-Day Service | Free Estimate
Frequently Asked Questions
Should I wait for an insurance adjuster to inspect the property before calling Floodline Restoration Co.?
No, policyholders are generally required by insurance contracts to take immediate steps to mitigate damage and prevent secondary mold or structural degradation. Floodline Restoration Co. provides 24/7 emergency dispatch and gathers carrier-standard photo and moisture documentation immediately so you can start drying without compromising your claim.
How does Floodline Restoration Co. handle water claim disputes involving older or pre-war buildings?
In pre-war homes with plaster-and-lath walls or balloon framing, adjusters often scrutinize deep-cavity moisture as pre-existing damage. Floodline Restoration Co. resolves these challenges by logging precise moisture migration patterns and physical evidence that prove the sudden nature of the discharge to your carrier.
Will I face unexpected out-of-pocket expenses when filing floodline restoration co insurance claims?
Floodline Restoration Co. minimizes surprise costs by compiling itemized, industry-standard scopes and communicating directly with your adjuster throughout the process. Policyholders are typically only responsible for their agreed-upon insurance deductible, with covered mitigation expenses submitted directly to the carrier.
About the author
 |
Marcus Caldwell Marcus Caldwell is an IICRC-certified Water Damage Restoration Technician with over 12 years of hands-on experience in emergency property recovery across New Jersey. Holding a B.S. in Construction Management from Rutgers University, he specializes in structural drying techniques and navigating complex insurance claims for both residential and commercial properties. Marcus leverages his field expertise to provide Englewood property owners with clear, actionable guidance on mitigating water damage and understanding restoration costs. |
Water damage, flood, or mold emergency?
We’re available now - call for a fast, free estimate.
Call Now - Free Estimate